Homeowner’s insurance is essential, there’s no way around it. Not only does it protect your home in the event of damage, but it also provides liability coverage if someone is injured on your property. When determining your premium, insurance companies assess various factors to gauge their risk and your cost. Some of these might seem logical, while others may surprise you. Here are seven factors that influence the cost of your homeowner’s insurance:
1. Square Footage
The size of your home is one of the most significant factors. A larger home costs more to replace if damage occurs, and it also tends to contain more belongings, furniture, and fixtures, all of which need to be covered under the policy.
2. Layout
The style and layout of your home also play a role. For example, a single-story home might have higher foundation and grading costs, whereas a two-story home could require alternative construction methods, influencing replacement costs.
3. Construction Materials
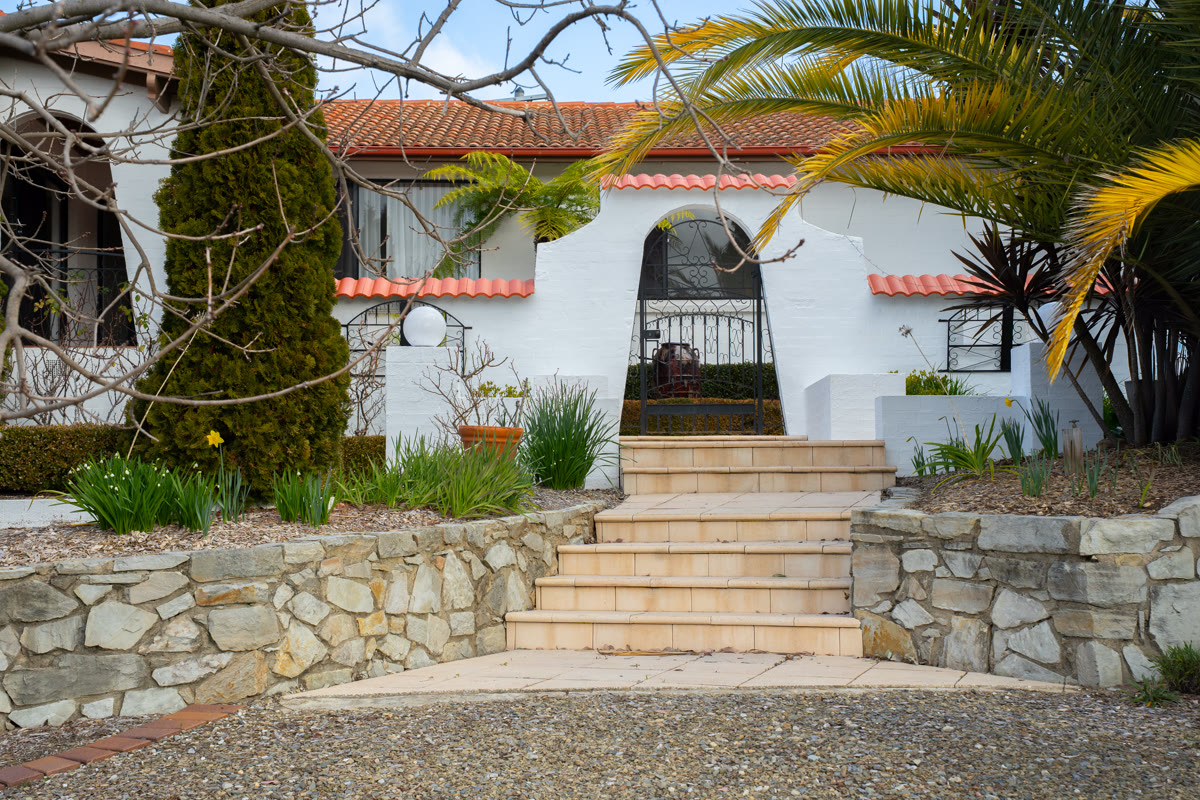
The materials used in your home’s construction impact the insurance premium. Homes with wood roofs or expensive materials like travertine floors may cost more to insure, as they’re more expensive to repair or replace in case of damage. Simpler homes with modest building materials are often cheaper to insure.
4. Property Age
Older homes are often considered higher risk due to potential deterioration and outdated systems. Newer homes, built with modern materials and safety codes, tend to be less expensive to insure because they’re assumed to be in better condition.
5. Home Features
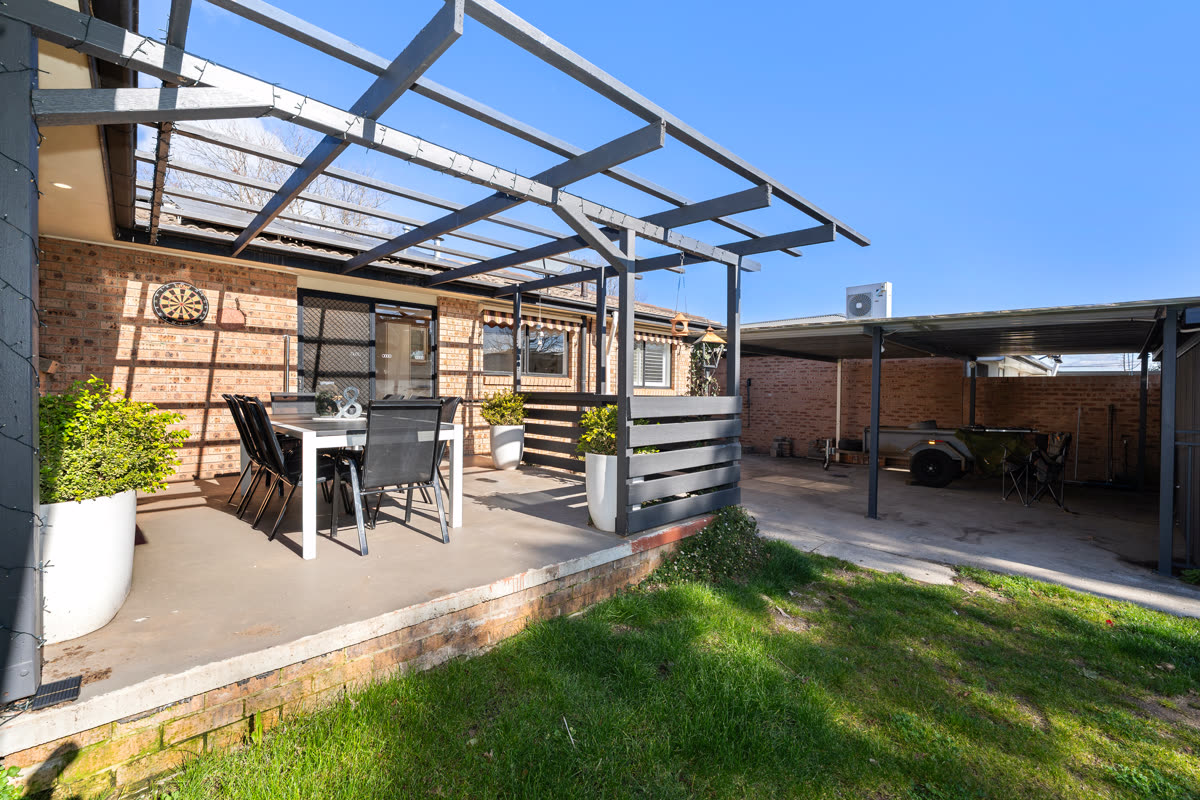
Homes with additional amenities like pools, sheds, or guest houses will usually see higher insurance costs. These extra features add more value to the property, which increases the replacement cost.
6. Neighborhood
The location of your home can affect your insurance premium. Homes in areas with higher crime rates or greater risk of natural disasters, such as flood zones, may have higher insurance premiums due to the increased likelihood of theft or property damage.
7. Credit Score
Your credit score plays a role as well. Insurers may view a higher credit score as an indicator of financial responsibility, which can lead to lower premiums. On the flip side, if your credit score is low, it might suggest to the insurer that you pose a higher risk of non-payment or may struggle with property upkeep.
Why Homeowner’s Insurance Matters
Homeowner’s insurance is not just a lender requirement, it’s crucial for your financial protection. It shields you from potential disaster, covering the costs of theft, fire, severe weather, and other unexpected damages. By understanding what influences your premium, you’ll be better equipped to compare policies and find the best coverage for your home.